The following describes the functionality and features included in Probe Audit Premium+
Instructions:
Objective
The objective of this document is to provide the senior member of the engagement team with a comprehensive checklist to confirm that all audit procedures have been completed, all documentation requirements have been met, and all relevant matters have been appropriately addressed before finalising the engagement.
The following key concepts of the Probe Audit Premium+ Methodology are set in this document:
-
First-level quality assurance review of completed audit work (ISA 220)
-
Verification that all audit procedures have been completed, documented, and audit objectives met
-
Confirmation that all required communications and representations have been obtained
Document placement
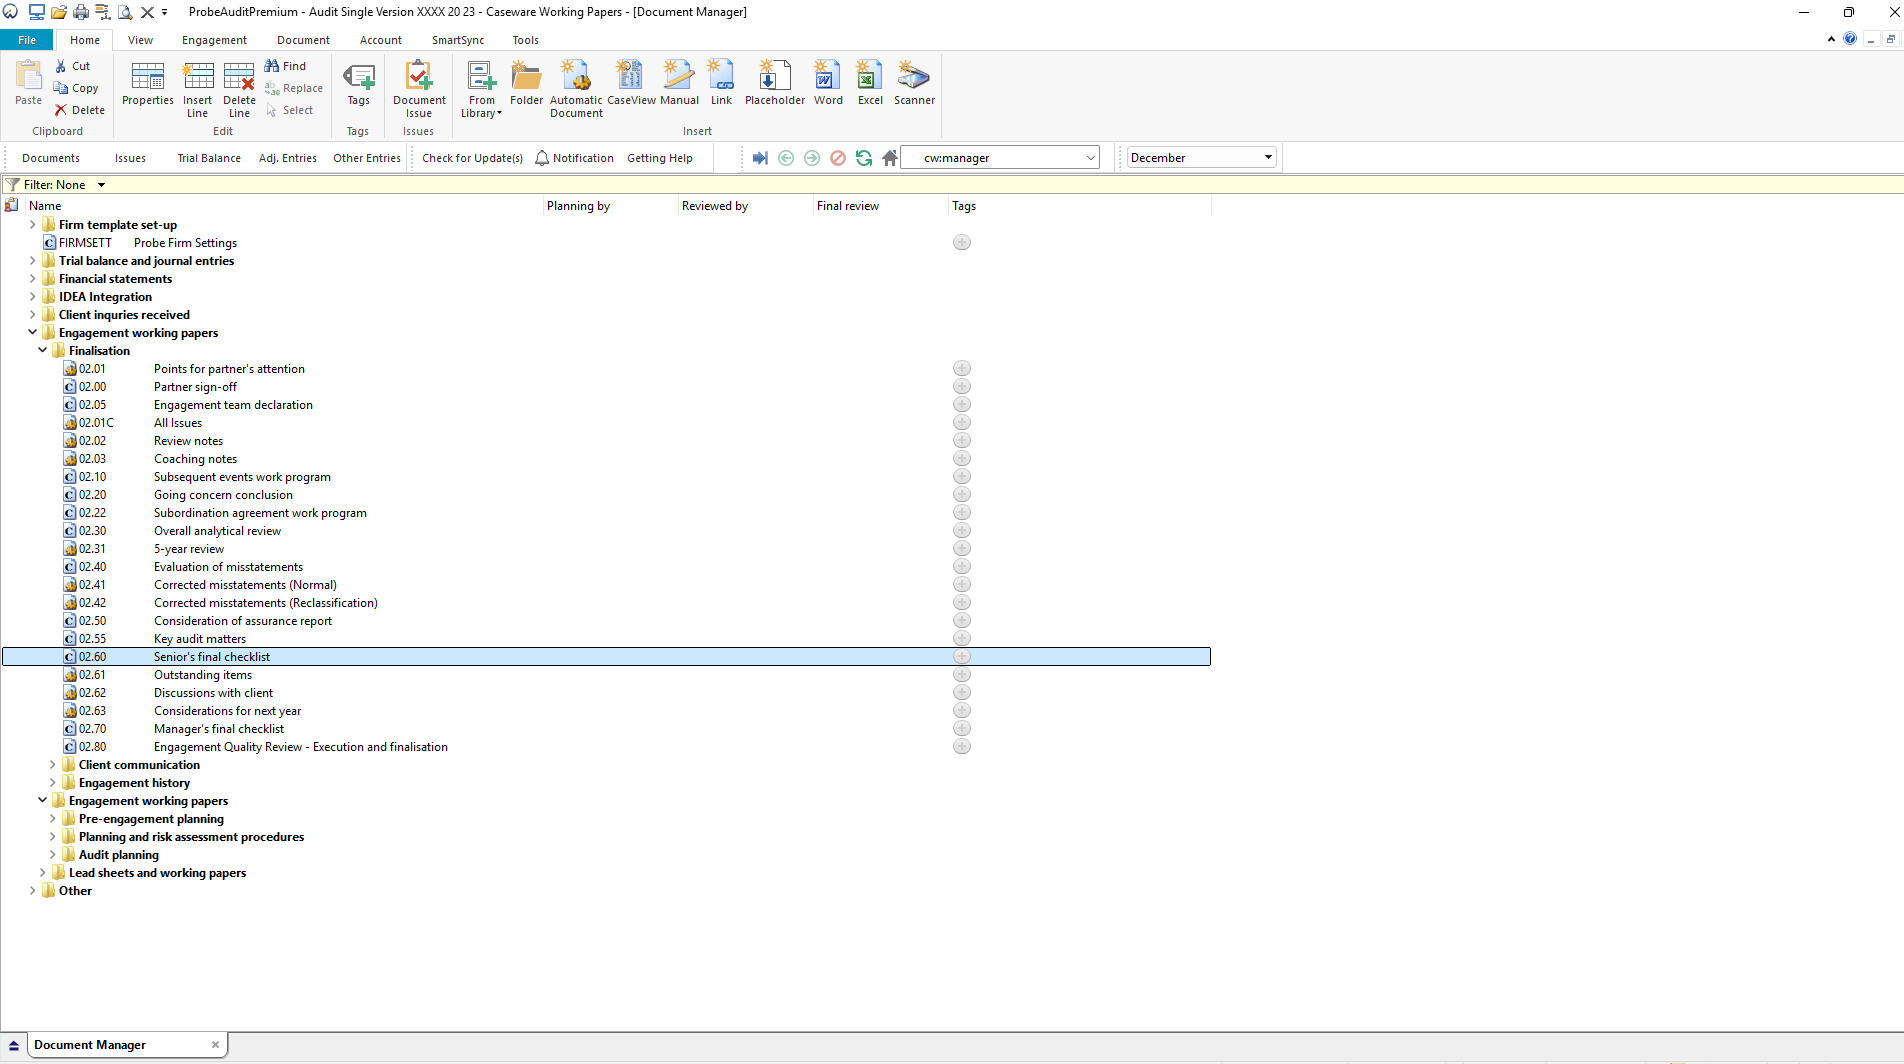
Document 02.60 – Senior’s Final Checklist can be found in the Finalisation folder in the Caseware document manager.
Document content
This document is designed to be a checklist type document that provides the senior member of the engagement team with a set of considerations to confirm that all audit procedures, documentation requirements, and reporting obligations have been completed before finalising the engagement.
The checklist covers a wide range of ISA requirements including ISA 200 (Overall Objectives), ISA 210 (Agreeing the Terms), ISA 230 (Audit Documentation), ISA 240 (Fraud), ISA 250 (Laws and Regulations), ISA 260 (Communication with Those Charged with Governance), ISA 315 (Identifying and Assessing Risks), ISA 320 (Materiality), ISA 330 (Responses to Assessed Risks), ISA 450 (Evaluation of Misstatements), ISA 500 (Audit Evidence), ISA 520 (Analytical Procedures), ISA 560 (Subsequent Events), ISA 570 (Going Concern), ISA 580 (Written Representations), and ISA 700 (Forming an Opinion).
Layout
|
Column
|
Input Required
|
Outcome
|
|
Considerations
|
No input is required in this column. The considerations are pre-populated and present the questions covering all aspects of the audit that the senior member of the engagement team must confirm have been completed. The questions address contracts and agreements, compliance with laws and regulations, internal control deficiencies, audit programs, opening balances, financial statement presentation, representations, misstatements, subsequent events, going concern, documentation, fraud, and file assembly.
|
No impact on the engagement file. Documents the considerations to be confirmed by the senior member of the engagement team before finalising the engagement.
|
|
Yes/No
|
Select 'Yes' or 'No' to confirm whether each consideration has been addressed. All considerations should be answered 'Yes' before the engagement is finalised.
|
No impact on the engagement file. Documents the senior’s confirmation that each consideration has been addressed.
|
|
Performed by
|
Populates automatically with the date and the initials of the engagement team member when Yes is selected for the conclusion question. When No is selected, click the cell to populate the date and your initials.
|
No impact on the engagement file. Records who confirmed each consideration and when it was confirmed.
|
|
Ref
|
Enter a cross-reference to the relevant working paper or supporting documentation for each consideration.
|
No impact on the engagement file. Documents the cross-reference for the engagement file.
|
Document outcomes
The senior member of the engagement team must confirm that all considerations displayed have been addressed by answering 'Yes' or 'No' to each question. All considerations should be answered 'Yes' before the engagement is finalised. Where a consideration is answered 'No', the engagement team must ensure that the matter is appropriately resolved before the engagement file is assembled and locked down. The checklist serves as evidence that the senior has reviewed all critical aspects of the engagement including compliance with ISAs, adequacy of documentation, communication with management and those charged with governance, and the appropriateness of the audit opinion.
Group Audits
When the engagement type was selected as 'Group Audit Single' or 'Group Audit Multiple', the senior’s final checklist applies to the group engagement. The engagement team must ensure that all considerations are addressed in the context of the group audit, including the involvement of component auditors and the adequacy of group audit documentation.
The group version of the checklist differs from the single-entity checklist in the following respects:
- Communication and reporting considerations refer to group management and those charged with governance of the group rather than management and directors, and the written representations are obtained from group management.
- The single-entity considerations on new procedures or changes to audit documentation after the date of the auditor's report, and on the inspection of board minutes and the director's authorisation of the financial statements, are not included in the group checklist.
Features
The following features are available in the document:
- Insert or delete a comment, see page F3
- Insert or delete a row, see page F4
- Edit paragraph or enable editing, see page F6
- Hide a paragraph or ignore a procedure, see page F8
- Guidance, see page F16
- Freeze, see page F19
Rate this article:
|vote=None|
Processing...
(Popularity = 0/100, Rating = 0.0/5)
Related Articles
Probe Audit | 02.60 Senior's final checklist
Probe | Finalisation | 02.60 Senior's final checklist
Probe Audit | 02.80 - Engagement Quality Review – Execution And Finalisation
Probe Audit | 12.40 - Engagement Quality Review – Planning (Audit)
view all...