The following describes the functionality and features included in Probe Audit Premium+
Instructions:
Objective
The objective of this document is to guide the engagement team through the procedures required to identify and evaluate subsequent events occurring between the date of the financial statements and the date of the auditor's report, and to document the conclusions reached.
The following key concepts of the Probe Audit Premium+ Methodology are set in this document:
-
Identification of events between the financial statement date and audit report date (ISA 560)
-
Evaluation of whether identified events require adjustment or disclosure in the financial statements
-
Impact of subsequent events on the audit opinion and audit report date
Document placement
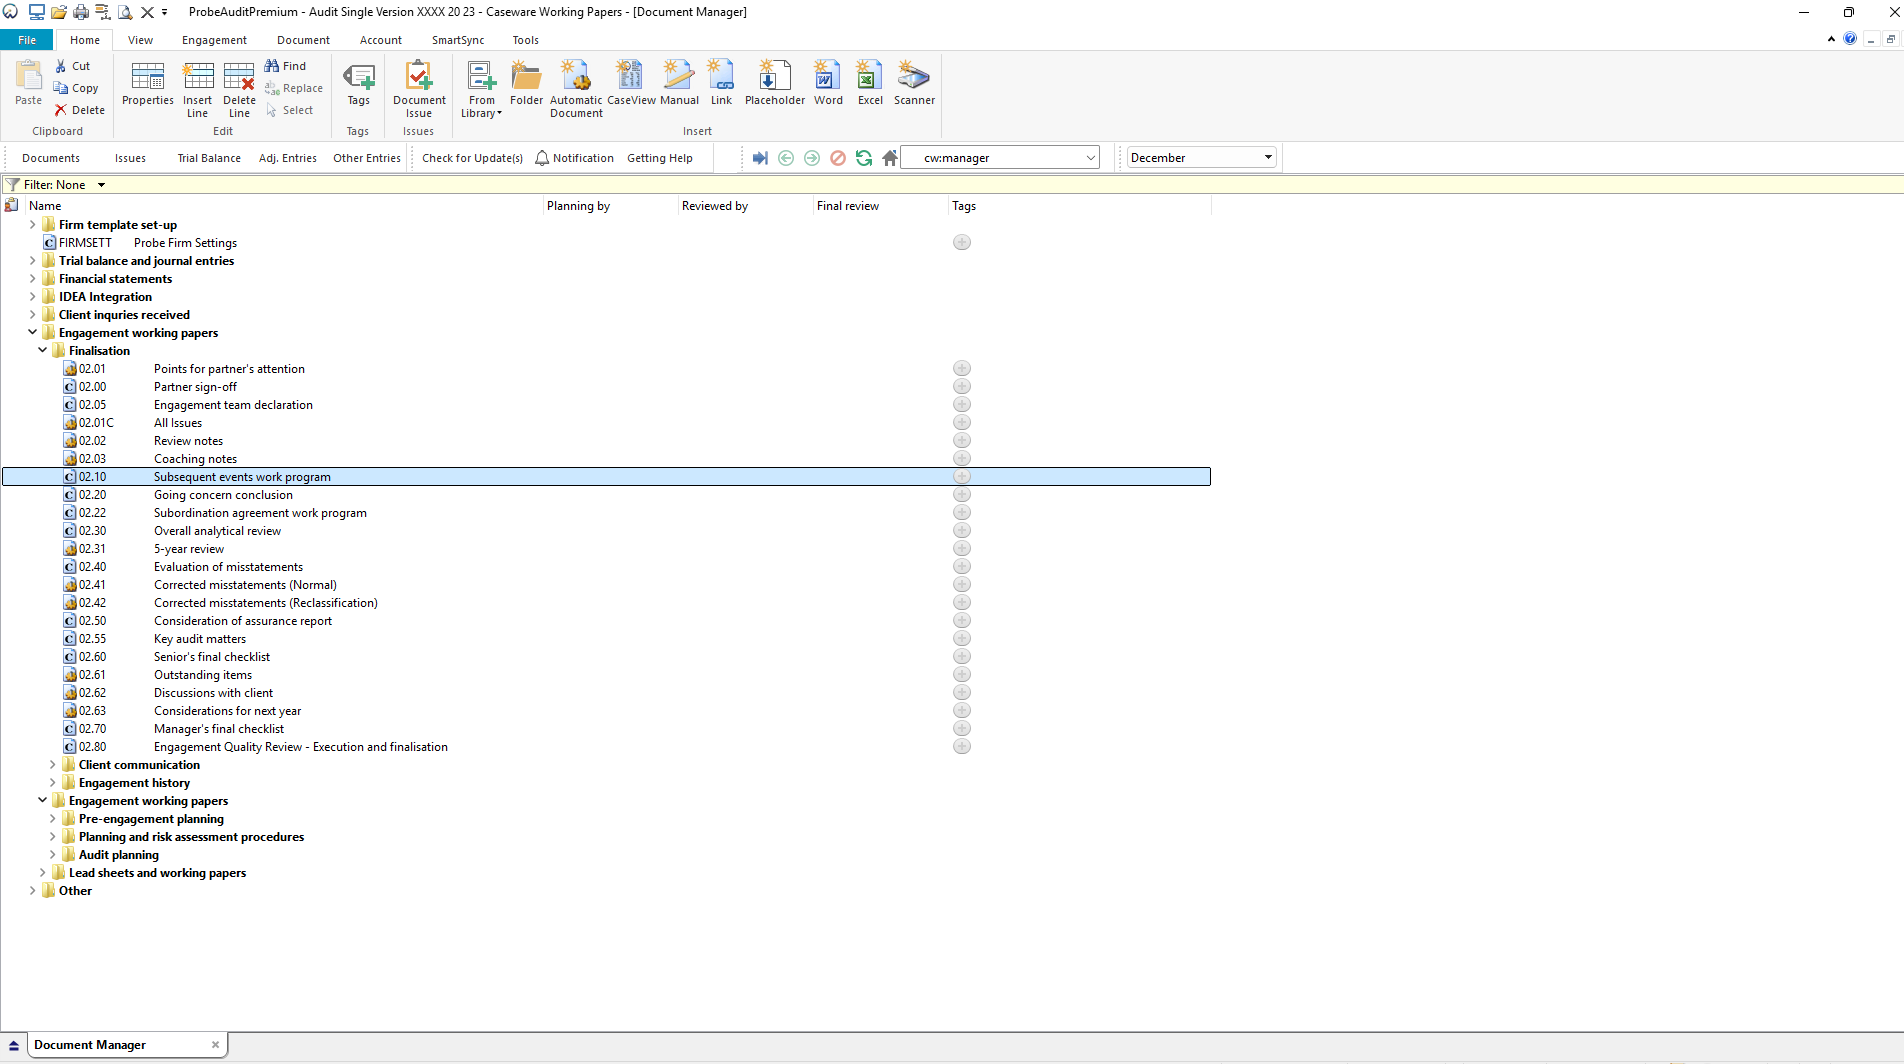
Document 02.10 – Subsequent events work program can be found in the Finalisation folder in the Caseware document manager.
Document content
This document is designed to be a CaseView work program with pre-populated audit procedures and space for comments, event recording, and cross-referencing.
This document addresses ISA 560 (Subsequent Events) by providing a structured set of procedures for identifying events occurring between the date of the financial statements and the date of the auditor's report. The procedures also reference the relevant requirements of the financial reporting framework selected for the engagement (IFRS or IFRS for SMEs).
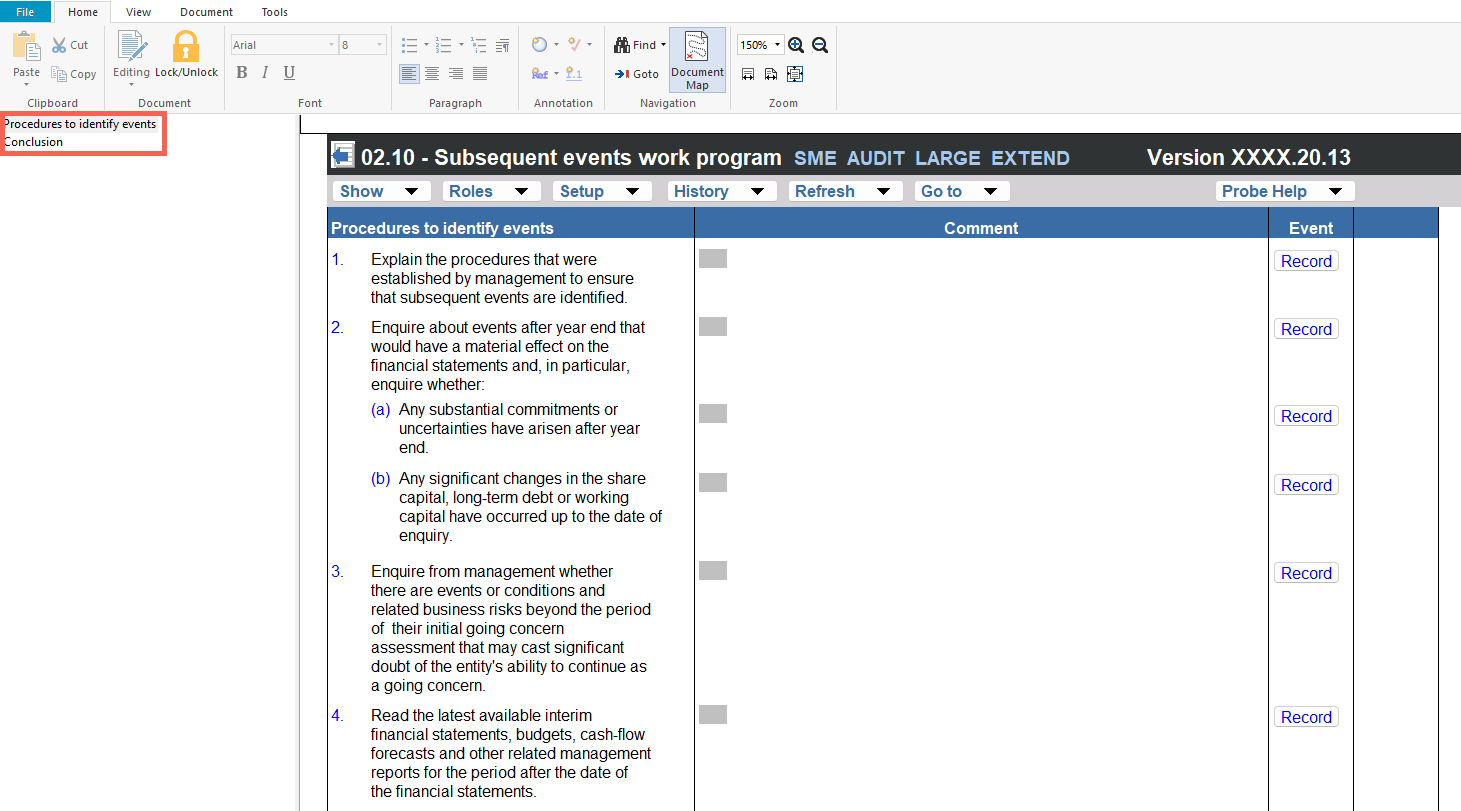
This document is divided into different bookmarks in the document map to assist you with navigation:
● Procedures to identify events
● Conclusion
Layout
|
Column
|
Input Required
|
Outcome
|
|
Procedures to identify events
|
|
Procedures to identify events
|
No input is required in this column. Displays the numbered audit procedures for identifying subsequent events. The procedures displayed depend on the financial reporting framework and engagement type selected, and address management enquiries, review of interim financial information, reading of minutes, obtaining written representations, enquiries of legal counsel, and review of adjusting and non-adjusting events in accordance with the applicable financial reporting framework.
|
No impact on the engagement file. Provides the structured work program for the engagement team to perform subsequent events procedures.
|
|
Comment
|
Enter comments or further details describing the work performed and findings for each procedure.
|
No impact on the engagement file. Documents the engagement team's comments and findings for each subsequent events procedure.
|
|
Event
|
Record an event in this column where a subsequent event is identified during the performance of the procedure. Once an event is recorded, the Events identified table appears at the bottom of the document.
|
Triggers the Events identified table at the bottom of the document, in which the event must be recorded, and replaces the pre-populated conclusion, which must be amended for the events identified. No other documents in the engagement file are affected.
|
|
Conclusion
|
|
Conclusion statement
|
No input is required in this column. Displays the pre-populated conclusion: "No subsequent events were identified that need to be recorded in the financial statements."
|
No impact on the engagement file. Provides the default conclusion for the engagement team's review.
|
|
Comment
|
Enter any comments relating to the conclusion on subsequent events.
|
No impact on the engagement file. Documents the engagement team's comment on the conclusion for the engagement file.
|
|
Events identified
|
|
Source
|
Select the working paper (from the document index) where the subsequent event was identified.
|
No impact on the engagement file. Documents the source of the subsequent event for the engagement file.
|
|
Events identified
|
Describe the subsequent event identified.
|
No impact on the engagement file. Documents the subsequent event identified for the engagement file.
|
|
Financial statement treatment
|
Record whether the event is an adjusting or non-adjusting event and the accounting treatment or disclosure required in the financial statements.
|
No impact on the engagement file. Documents the engagement team's assessment of the financial statement treatment of the event.
|
|
Conclusion
|
Document the engagement team's conclusion on the subsequent event identified.
|
No impact on the engagement file. Documents the engagement team's conclusion on the event for the engagement file.
|
|
Ref.
|
Select a cross-reference to the working paper or supporting documentation for the event.
|
No impact on the engagement file. Documents the cross-reference for the engagement file.
|
Document outcomes
The engagement team must perform the subsequent events procedures and document their comments for each procedure performed. Where an event is identified, the engagement team must record the source, description, financial statements treatment, conclusion and cross-reference for each event in the Events identified table at the bottom of the document. The procedures cover management enquiries regarding events after year end, review of interim financial information, obtaining written representations, enquiries of legal counsel, and evaluation of adjusting and non-adjusting events in accordance with the financial reporting framework selected for the engagement.
The engagement team must review the pre-populated conclusion and confirm that no subsequent events were identified that need to be recorded in the financial statements or amend the conclusion where subsequent events have been identified.
Group Audits
When the engagement type was selected as 'Group Audit Single' or 'Group Audit Multiple', the subsequent events work program applies to the group engagement. The engagement team must perform the subsequent events procedures for the group financial statements. The procedures included depend on the engagement type, the financial reporting framework and other answers in the engagement file. The group version of the work program differs from the single-entity version as follows:
● The procedures refer to 'group management' and 'the group' instead of 'management' and 'the entity', including the enquiries about the going concern assessment and of the group's legal counsel.
● An additional procedure is included to scrutinise transactions, events and conditions occurring after the reporting date up to the date of the auditor's report that provide evidence of the fair presentation of accounting estimates and related disclosures at the reporting date.
● The single-entity procedure to ensure that adjusting events have been recognised in accordance with the financial reporting framework, together with its sub-procedures (settlements of court cases, sales of inventories, proceeds and costs of assets, employee benefits and fraud or errors detected), is not included in the group version.
● The procedure on meetings held after the date of the financial statements requires the engagement team to read the minutes of those meetings rather than to enquire about the matters discussed.
Features
The following features are available in the document:
● Insert or delete a comment, see page F3
● Insert or delete a row at the end, see page F5
● Guidance, see page F16
● Freeze, see page F19
Rate this article:
|vote=None|
Processing...
(Popularity = 12/100, Rating = 0.0/5)
Related Articles
Probe Methodology | Finalisation - 02.10 Subsequent events work program in probe
Probe | Finalisation | 02.10 Subsequent events work program
Probe Audit | 02.10 Subsequent events work program
Probe Audit | 750.11 - Wage Payout Work Program
view all...
Search Results
Investec Private Bank South Africa Audit Confirmation Instructions
RMB Investment and Corporate Banking South Africa Audit Confirmation Instructions
Citibank South Africa Audit Confirmation Instructions
Standard Bank South Africa Audit Confirmation Instructions
ABSA Corporate Bank South Africa Audit Confirmation Instructions
view all...